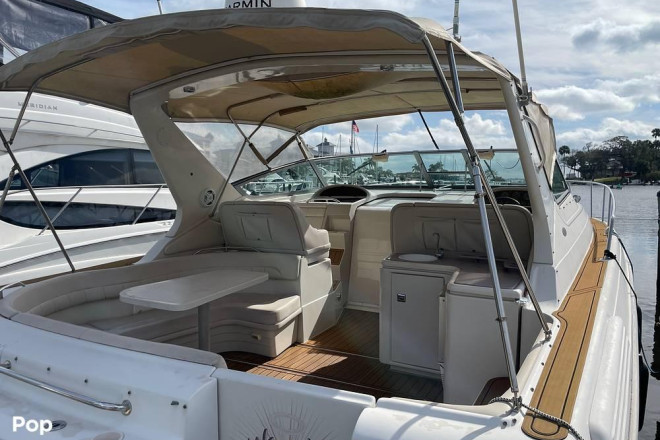
Owning a boat is a dream for many, offering endless opportunities for adventure, relaxation, and quality time on the water. However, the cost of purchasing a boat can be a significant investment. Fortunately, flexible financing options are available that can make owning a boat more accessible than ever. By understanding the various financing options, potential boat owners can navigate the process with confidence, ensuring a purchase that not only fits their lifestyle but also their financial situation.
Understanding Boat Financing Options
When considering boats for sale with financing, it’s crucial to understand the different types of financing available. Each option can vary in terms of interest rates, loan terms, and qualifications, so it’s important to find the one that best suits your financial situation.
Types of Boat Loans
- Secured Loans: These loans use the boat as collateral, potentially offering lower interest rates. However, failure to repay the loan could result in the loss of the boat.
- Unsecured Loans: These loans do not require collateral but often come with higher interest rates due to the increased risk for the lender.
- Home Equity Loans: Homeowners may use the equity in their home to secure a loan, often resulting in favorable interest rates. This option requires a careful assessment of the risks involved.
- Dealer Financing: Many dealers offer financing options directly, which can be convenient and occasionally include promotional offers or rates.
Benefits of Flexible Financing
Flexible financing provides several advantages that can help make boat ownership more feasible.
- Customizable Payment Plans: Tailor the loan duration and monthly payments to fit your budget and financial goals.
- Competitive Interest Rates: With a good credit score, borrowers can secure competitive rates that minimize the overall cost of the loan.
- Quick Approval Process: Many lenders offer streamlined approval processes, allowing potential boat owners to receive funding and purchase their dream boat without long delays.
Preparing for the Loan Application
Before applying for a boat loan, it’s important to be prepared and understand what lenders typically require. This preparation can make the application process smoother and increase the chances of approval.
Key Considerations
- Credit Score: A good credit score can significantly improve the terms of the loan. Consider obtaining a credit report and addressing any issues before applying.
- Down Payment: A larger down payment can reduce the loan amount and potentially secure better loan terms. Determine how much you can afford to put down on the purchase.
- Income Verification: Lenders require proof of income to assess the borrower’s ability to repay the loan. Gather necessary documents such as pay stubs or tax returns.
Choosing the Right Boat
When exploring boats for sale with financing, it’s crucial to select a vessel that meets both personal and financial criteria. Consider factors such as the intended use of the boat, storage, and maintenance costs, as these will impact the overall ownership experience.
Factors to Consider
- Size and Type: The size and type of boat should align with the intended activities, whether it’s fishing, sailing, or cruising.
- New vs. Used: Consider whether a new or used boat better fits your budget and preferences. Used boats can be more affordable, but may come with additional maintenance needs.
- Maintenance Costs: Calculate ongoing costs such as docking, insurance, and upkeep, ensuring they fit within your financial plan.
By understanding and leveraging flexible financing options, aspiring boat owners can achieve their dream of owning a boat. With careful planning and informed decision-making, the water awaits for endless adventures and memorable experiences.